Photo by Jeffrey F Lin on Unsplash
Several months ago I saw two different couples who were very similar in many ways. The similarity that stood out to me most was that both couples were spending a substantial amount of money on expensive activities for their children, despite each being in a precarious financial situation – including a lot of credit card debt.
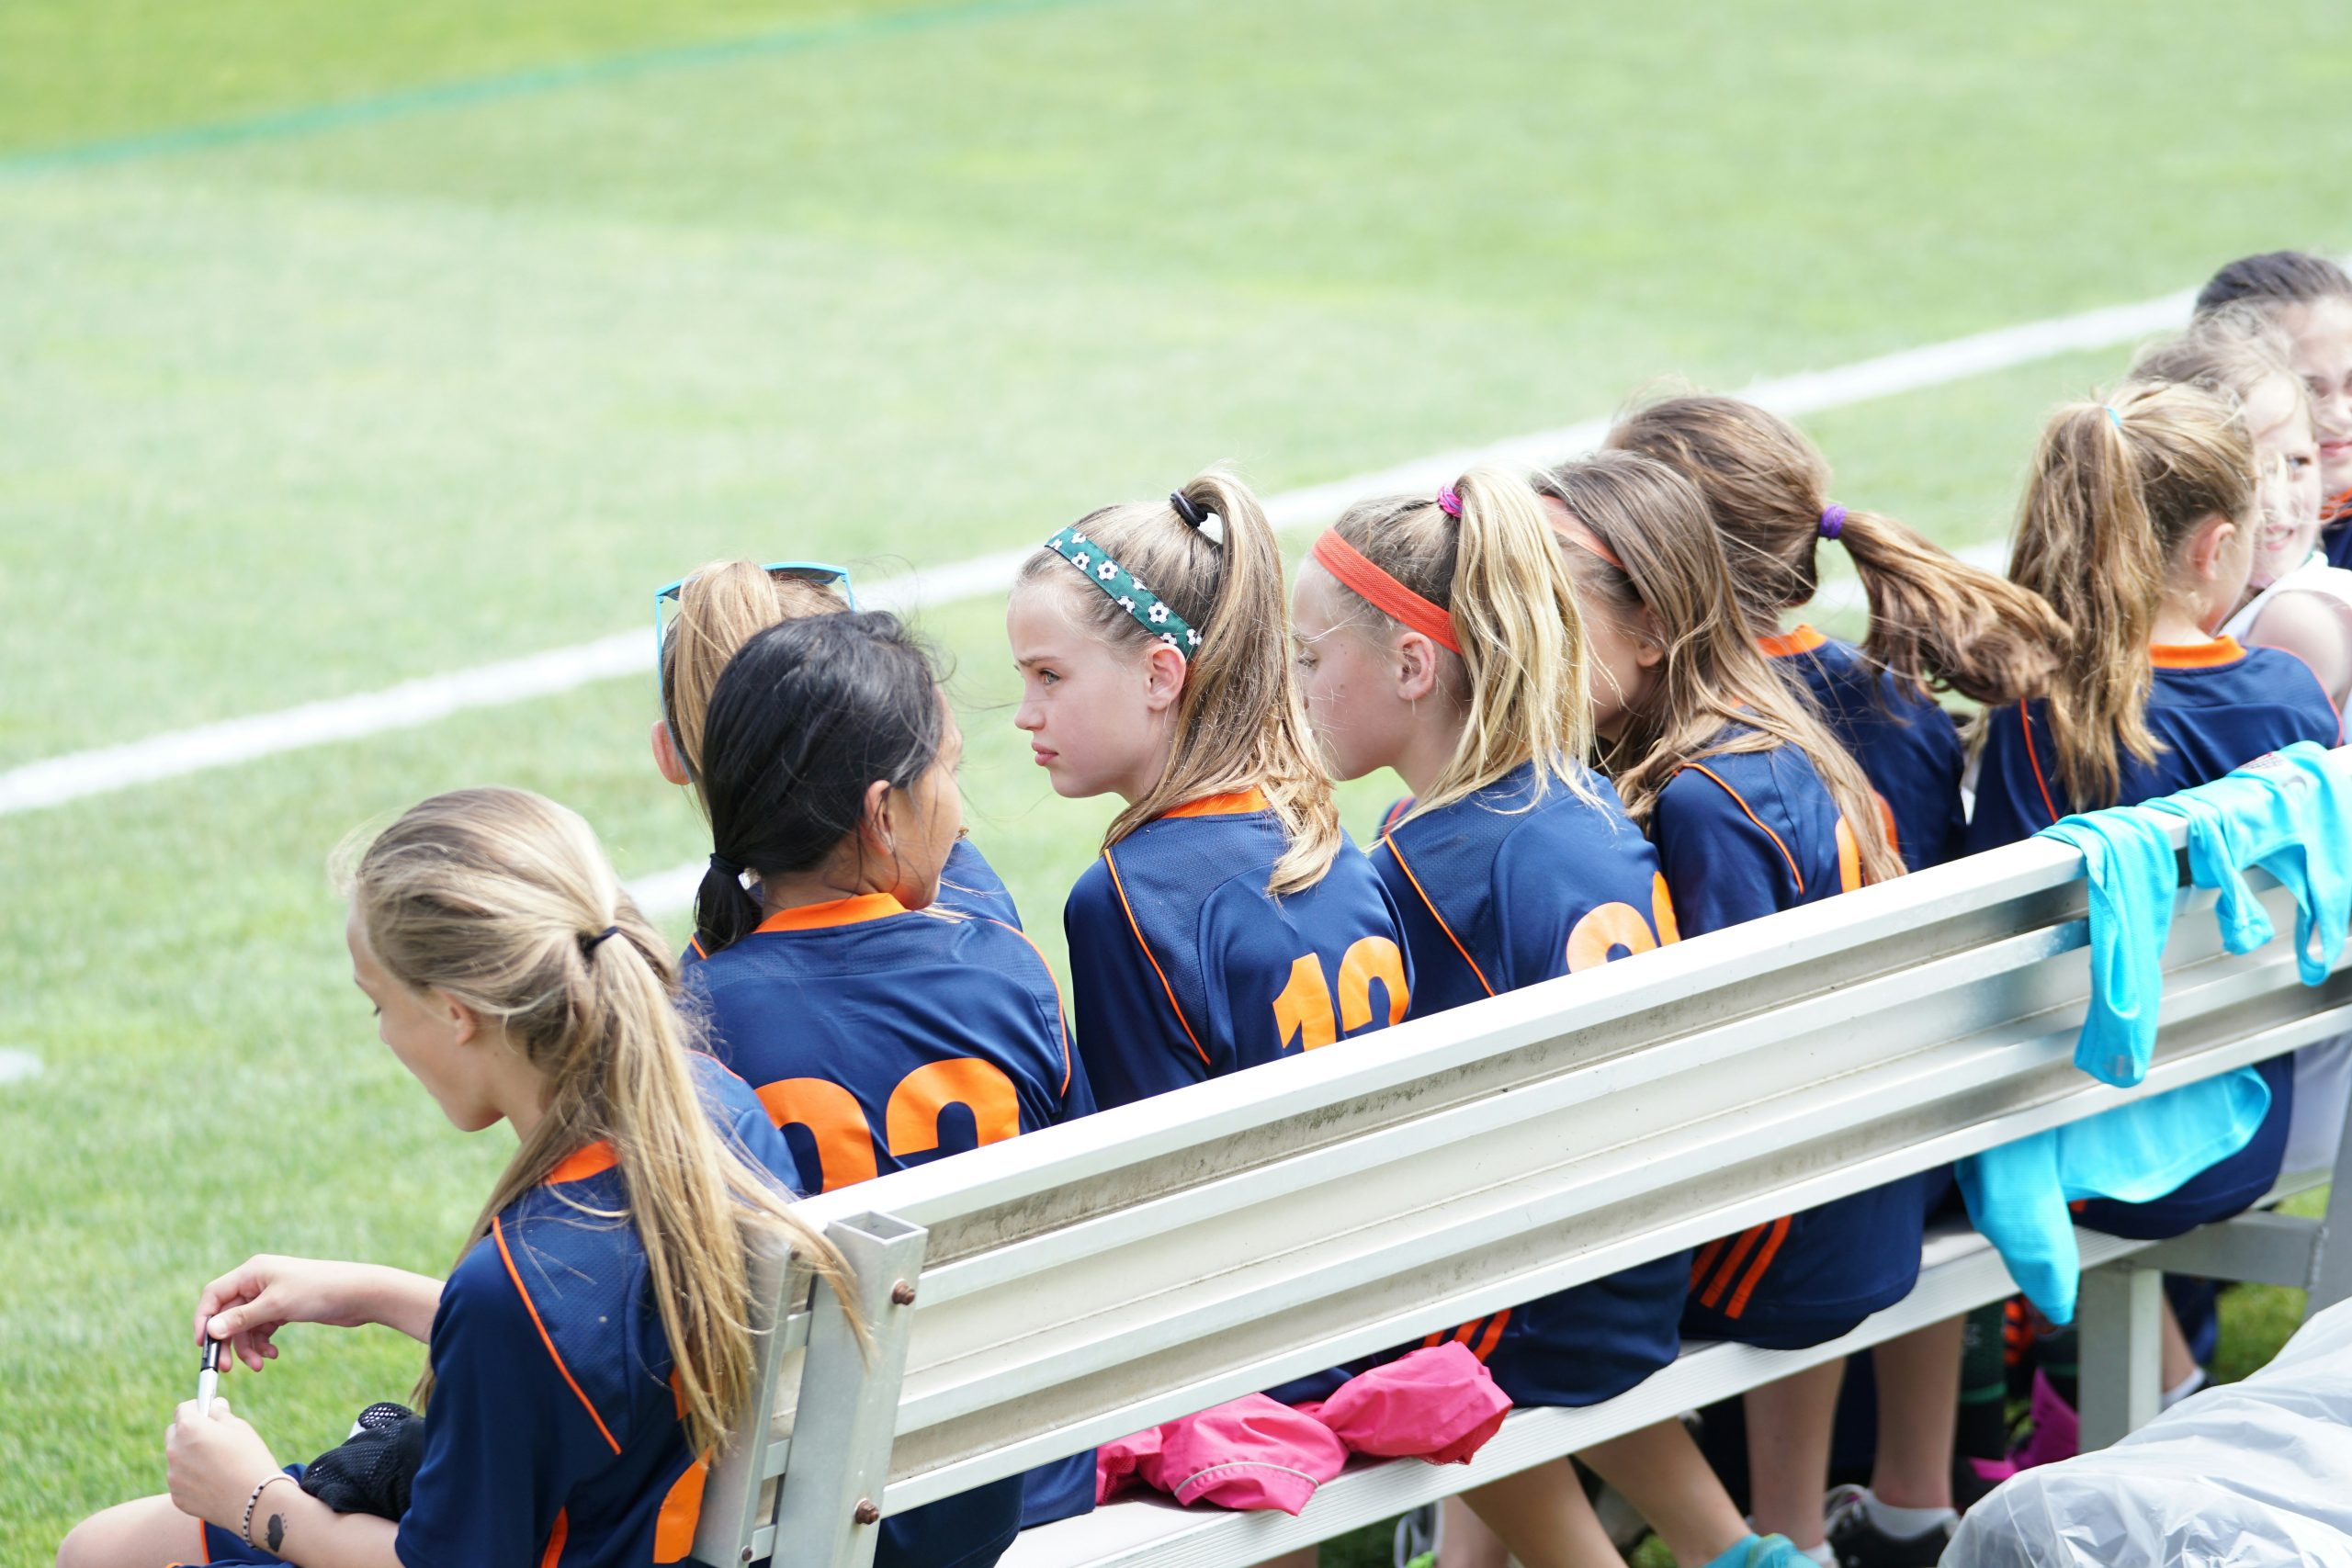
You’re probably familiar with the kinds of activities I’m talking about – travel soccer or hockey, or competitive cheer or dance. The kinds of activities that not only carry expensive direct costs in order to participate, but also require frequent travel, which brings hotel stays and restaurant meals. Some even have long-distance travel by plane for competitions. The parents are also usually expected to pay for uniforms or costumes or other equipment.
On occasion I’ve seen adults who have their own expensive hobbies, but those expenses tend to be far more modest; they’re usually for weekly lessons or occasional supplies, and don’t often come with a lot of travel expenses. They also are willing to cut back if their budget get tighter. The activities for children are unique in the size of the related expenses and the willingness parents have to spend substantial amounts of their income.
If you’re familiar with me at all, you know I’m the mom of four – at the moment my kids range in age from 16-21. I’ve been faced with these choices myself. Our particular one was soccer. We opted out due to the cost and the time commitment of travel soccer. My little Messi had to be satisfied with the community youth program, and then the teams at the public school.
Other people have different priorities than me; for some parents who spend thousands of dollars per year it’s likely that they just see their child loves their sport and they want to allow them to participate as much as possible. Sometimes parents think that paying for these programs is actually an investment; they’re convinced that colleges will fall all over themselves with scholarship money.
I’m not a person who insists that my clients ruthlessly cut out all discretionary spending if they have debt. I don’t think it’s sustainable, and is likely to backfire. It’s their money; I can point out changes that I might consider, but I don’t get to make decisions for them. My job is to lay out their choices and help them understand the consequences of each. For many parents, cutting out activities that are so important to their children is absolutely off the table. I have to accept that and work with it.
My goal when working with people like this is to get them to save intentionally ahead of time, and to be more mindful of their spending. A lot of times the mindset is that they spend whatever it takes, and they carry credit card debt. They treat it like a fact of life.
With clients like this, I separate the debt from future expenses. These are two distinct issues. First we talk about the existing debt and how much they can put towards it on a monthly basis, and how long it will take them to pay off under that plan. That’s the easy part.
I emphasize that continuing to casually spend is not a sustainable strategy; sometimes they’re literally running out of available credit and they can see that there has to be an end in sight to this level of spending. They’re approaching maxing out their cards, and they know they won’t be approved for more.
Oftentimes these activities aren’t fully year-round. They may run for six or eight months, but there is usually a break. Luckily for both of the couples I mentioned up top, the seasons had just ended and they had several months without any activity-related costs at all. First I had them quantify how much they spend on the activity in a year: fees, travel, equipment. Then we broke that down into monthly amounts, and I encouraged them to set up a separate bank account for this purpose. Let’s say they were spending $4,500 per year on this sport. They need to put aside $375 per month into a bank account to be used only for this purpose. A lot of times the bigger travel expenses happen a little later in the season, so it gives them time to save up.
Ideally they would then use the balance in that bank account to make choices when planning travel. Maybe that means booking a cheaper hotel than the rest of the team; maybe it means bringing just one parent and no siblings along when the entire family has always traveled together. Or they bring food instead of eating out. One other possibility: a parent picks up a second job to cover these costs. That’s not an appealing idea for many busy parents, but it would solve a lot of their problems.
Am I optimistic that they’ve seen the light and will perfectly follow this plan? They’ll set money aside and stick to it? Honestly, I have mixed expectations. One couple seemed more excited about the idea of stemming the bleeding and I believe they’ll try; I think the other thought it was unrealistic and hopeless. When you’ve been living a certain way for a long time and spending without considering the consequences, it’s really hard to change. I try to show them a world in which it’s possible for them to be able to give their children what they want in a financially responsible way, but sometimes people don’t believe me or they think I can’t possibly understand their situation.
I believe that most people can spend their money on things that are important to them without jeopardizing their financial security. They just need to be realistic about the costs and what they can afford, and come up with a workable plan for funding their choices.
